The NWA Land Squeeze:

Why Northwest Arkansas's Housing Boom Has a Lot Problem


Northwest Arkansas has been one of the fastest growing regions in the country for most of the last decade, and the numbers keep proving it out. According to the Northwest Arkansas Council, the region is now adding about 40 new residents a day, and population has climbed past 622,000 as of late 2025. Fortune 500 employers like Walmart, Tyson Foods, and J.B. Hunt keep pulling relocations into Bentonville, Rogers, Springdale, and Fayetteville. Bentonville alone grew from just over 54,000 residents in the 2020 Census to nearly 62,000 by 2024, a 14% increase in four years, per Census Bureau estimates. Centerton has ranked among Arkansas's fastest growing cities for several years running, and cities like Pea Ridge have nearly doubled in size since 2020.

That's the growth story every investor in this market has already heard. What gets far less attention is what's happening underneath it. The region isn't producing enough finished, buildable lots to keep pace with the people moving here.


A Widening Gap Between Demand and Buildable Ground


4,800

BUILDABLE LOTS

40

NEW RESIDENTS DAILY

$239M

SEWER INFRASTRUCTURE

The most recent Skyline Report, the semiannual benchmark for Northwest Arkansas real estate compiled by the University of Arkansas, counted roughly 22,000 total lots in active subdivisions across Benton, Washington, and Madison counties. Only about 4,800 of those lots are actually vacant and ready to build on. The rest are already occupied, under construction, or complete and sitting unsold.

CBER's own inventory math bears that out. Across every lot and home in the pipeline that isn't yet occupied, the region carries under two years of supply, 20.7 months, at the current absorption rate. That's a tight number for a region adding roughly 40 new residents every day. For a builder who isn't already sitting on a land position, there is functionally nowhere to buy ground and start building tomorrow.

It shows up directly in price. The average home price in Benton County reached $471,427 in the first half of 2025, up 8.9% year over year, while Washington County averaged $417,489, up 7.2%. New construction made up only about a third of homes sold in the back half of 2025, the lowest share in the last five reports, with resale inventory absorbing the rest. When population growth consistently outpaces the pipeline of new, buildable lots, rising prices aren't a temporary correction. They're the structural result, and nothing in the current entitlement and development pace suggests that's changing soon.


Water and sewer capacity is adding another layer to that constraint. Centerton's growth outpaced its wastewater capacity to the point that state regulators stopped approving new projects tied to its treatment plant, and Bentonville is now financing a $239 million overhaul of its own sewer system, expected to take a decade, just to keep up with demand. It's a reminder that raw land doesn't become a buildable lot on capital alone. It takes an operator who knows how to work through entitlement and infrastructure timelines, not just write a check.

Who Actually Controls the Lots
“The demand is there. The constraint is control of the supply.”

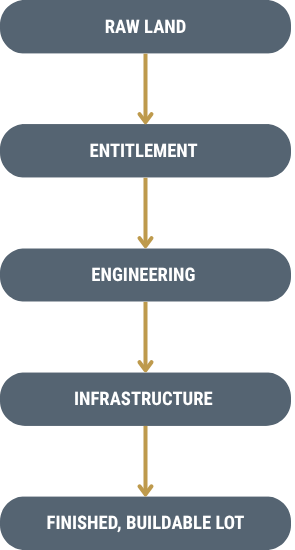
Primario Capital's flow chart

Here's the part of the story that matters most to how Primario Capital operates. The lots

that do reach the market aren't being created by the builders who need them. They're created by developers, separate businesses whose entire model is acquiring raw ground and taking it through entitlement, engineering, and infrastructure to deliver a finished, buildable lot.

Smaller and mid-size builders, the ones actually building the product diversity this market needs, from workforce housing to CrossMod® communities to attainable single-family homes, mostly can't access that pipeline at all. With only a couple thousand truly vacant lots in play across the region at any given time, and national builders positioned to buy in bulk, direct from developers, before anything is ever publicly listed, a smaller builder without an existing land position is effectively locked out. For them, the only real path to consistent lot supply is to buy finished lots from someone who develops them or become a developer themselves.

National builders solve the same problem differently, and they solve it with more resources. A public homebuilder's entire growth model depends on a steady, predictable feed of finished lots, and in a market, this supply constrained, they can't count on organic subdivision turnover to keep their construction and sales pipeline full. That's why they're constantly in the market to acquire land directly, buy out smaller developers, or lock up entire finished developments in bulk, whatever it takes to keep the machine fed. Whether that lot supply comes from their own in-house land division or from an outside developer, the lots still have to be sourced and entitled by somebody. That demand doesn't go away when the market tightens. It gets more aggressive. It isn't that demand for buildable lots is missing on either end of the market. It's that almost nobody outside the largest players controls enough of the supply to meet it, and that gap is exactly the market Primario Capital was built to serve.
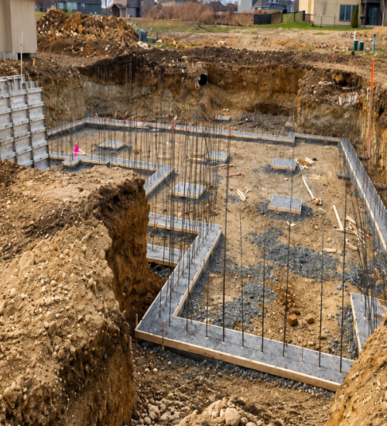
Aerial view of residential homes under construction

Where Primario Capital Fits

This is exactly the gap Primario Capital is built to close. Most capital sitting on the sidelines in this market is looking for a finished lot to purchase. Primario Capital works the stage before that. We source raw and underutilized land directly, take it through entitlement and development ourselves, and deliver finished lots.

That gives every project three ways to create value instead of one. We can sell finished lots directly to the smaller and mid-size builders who have no other reliable way to secure ground. We can sell finished lots or entire completed developments to national builders who need to keep their pipeline fed and don't have the time or local team to develop it themselves. Or we can hold the lots and build the homes ourselves through our affiliated construction operations, putting product directly into the market instead of selling the ground to someone else. Which path we take is decided project by project, based on which one produces the better outcome, not locked in from day one the way it would be for a fund that only buys, only sells wholesale, or only builds.

Built by 21 Years of Construction Experience
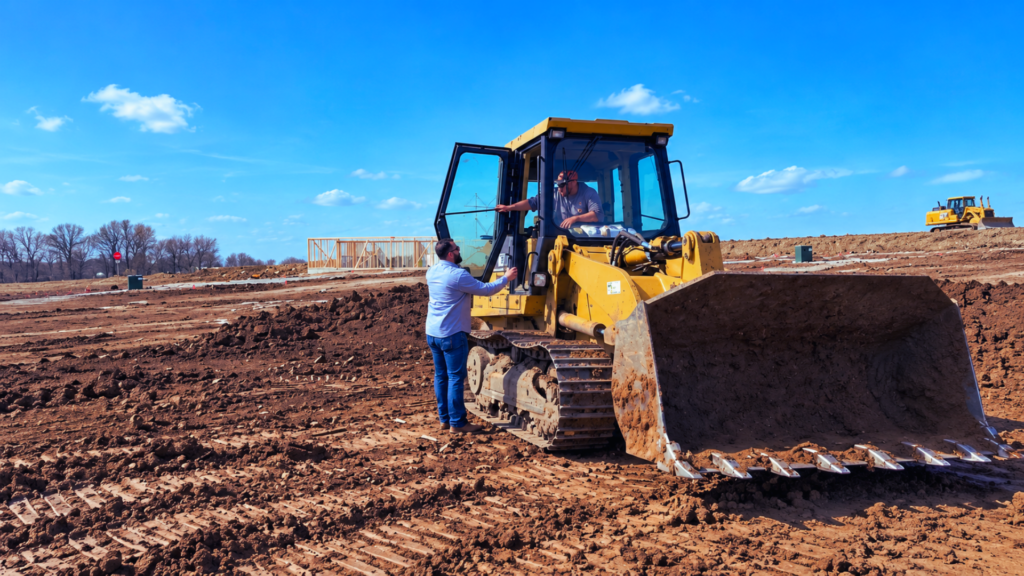
Damon in a work site

That flexibility is only as good as the team executing it. Land development isn't a financial modeling exercise. It's entitlement timelines, utility and infrastructure sequencing, realistic construction cost estimating, and knowing which sites actually pencil once grading, septic or sewer capacity, and municipal permitting requirements are accounted for.

That's the core difference between Primario Capital and a purely financial sponsor. We're not a group with capital and no boots on the ground. We're an operator first, which gives investors direct visibility into how a project is actually being built and how risk is being managed, not just a return projection on a pitch deck.

A Platform Built Around Its Own Projects
Primario Capital doesn't fund outside deals or act as a passive lender into someone else's development. Every project in the fund is one we source, control, and manage ourselves, from acquisition through exit. That means investors are backing a team with real operating experience on the ground in this exact market, not a blind pool chasing whatever deal comes across the desk next.

Northwest Arkansas' growth isn't slowing down, and the lot shortage behind it isn't a short-term supply hiccup. It's a structural condition that's been building for the better part of a decade. The opportunity belongs to whoever can source and develop ground directly instead of waiting on someone else's pipeline. That's the position Primario Capital has built itself to hold, with three ways to put every project to work.

PRIMARIO CAPITAL FUND 1

Open to Accredited Investors

Learn more about current projects and the fund.

This material is for informational purposes only and does not constitute an offer to sell, or a solicitation of an offer to buy, any securities. Any such offer will be made only to accredited investors by means of a confidential Private Placement Memorandum, pursuant to Rule 506(c) of Regulation D under the Securities Act of 1933. Primario Capital Fund 1 LLC has not been registered with the SEC or any state securities regulator. An investment in the fund involves a high degree of risk, including the possible loss of principal, and is suitable only for investors who can bear that risk. Past performance and market conditions described here are not indicative or guarantees of future results. All prospective investors must independently verify their accredited investor status and review the Private Placement Memorandum in full before investing.

©2026 Primario Capital. All Rights Reserved.

Disclaimer: The information contained herein is provided for informational purposes only, is not complete, and does not contain certain material information about the opportunity, including important disclosures relating to the risks, fees, expenses, liquidity restrictions and other terms of investing in the opportunity, risks and potential conflicts of interest. The information contained herein is provided for discussion purposes only and is subject to change without notice. The information contained herein does not consider the investment objectives or the financial condition or other circumstances of any individual investor. This document does not constitute an offer of investment advisory services by Primario Capital or its affiliates, nor does it constitute an offering of interests. Any such offering is made solely pursuant to the private offering memorandum and definitive governing agreements of Primario Capital (the “Fund”). An investment in the Fund is suitable only for qualified investors that fully understand the risks associated with such an investment. All investments carry a certain degree of risk and investors should review the private offering memorandum and their own investment objectives, risk tolerance, tax objectives and liquidity needs with their investment advisor before making an investment decision. No chart, graph or other figure provided should be used to determine which securities to buy or sell. Unless indicated to the contrary, all opinions, beliefs, data and information is subject to change without notice. Nothing contained herein is intended to be, and you should not consider anything contained herein to be, investment, accounting, tax or legal advice. This document is intended solely to provide general information regarding Primario Capital and the Fund. Primario Capital does not solicit or make its services available to the general public. Under no circumstances should any information provided herein be used or considered as an offer to sell or a solicitation of an offer to buy an interest in the Fund or any other security. Although this information may include investment-related information, nothing provided herein is a recommendation that you purchase, sell or hold any security or other investment, or that you pursue any investment style or strategy. This document is confidential, is intended solely for the person to whom it has been sent and may not be shown, copied, transmitted, or otherwise given to any person other than the authorized recipient. Certain information contained in these materials has been obtained from published and non-published sources prepared by third parties, which, in certain cases, have not been updated through the date hereof. While such information is believed to be reliable, Primario Capital has not independently verified such information, nor does it assume any responsibility for the accuracy or completeness of such information. Except as otherwise indicated herein, the information, opinions and estimates provided in this presentation are based on matters and information as they exist as of the date these materials have been prepared and not as of any future date and will not be updated or otherwise revised to reflect information that is subsequently discovered or available, or for changes in circumstances occurring after the date hereof. Primario Capital’s opinions and estimates constitute Primario Capital’s judgment and should be regarded as indicative, preliminary and for illustrative purposes only. Past performance is not necessarily indicative of future results and there can be no assurance that targeted returns will be achieved. There can be no assurance that the Fund will achieve results comparable to or that the returns generated will equal or exceed those of other investment activities of Primario Capital or its affiliates or that the Fund will be able to implement its investment strategy or achieve its investment objectives. Primario Capital does not make any representation or warranty, express or implied, regarding future performance. Targeted investor returns shown herein are based on assumptions and calculations of Primario Capital using data available to it. Targeted returns are subjective and should not be construed as providing any assurance to the results that may be realized by the fund in the future. Statements contained herein that are not historical facts are based on current expectations, estimates, projections, opinion or beliefs of Primario Capital as of the date indicated. By using or relying on this information, the reader agrees that Primario Capital shall have no liability for the accuracy of the information contained herein, for delays or omissions therein, or for any results based on the use of, or reliance on, such information. To the extent any information herein represents, or is based upon, “forward-looking statements” or information (which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipation,” “project,” “estimate,” “intend,” “target” or “believe” or comparable terminology), please note that, due to various risks and uncertainties, actual events, results or performance may differ materially from those reflected or contemplated in such forward-looking statements or information. In addition, past or projected performance of Primario Capital and its principals is not necessarily indicative of future results. Primario Capital makes no guarantee that the Fund or any of its investments will be able to achieve these targets. Targets are objectives and should not be construed as providing any assurance as to the results that may be realized in the future from investments in the Fund. The results of the Fund and its investments may differ significantly from any performance data provided or referenced herein due to a number of factors and any such difference may be material. Investors can lose their investment in whole or in part.